Two provisions stand out as especially damaging.
First, South African businesses would be barred from using digital assets for cross-border payments that are treated as imports or exports of capital, even when the same commercial activity is perfectly legal if settled through a bank.
A software company invoicing a foreign client in stablecoins, or a trader settling with an African supplier over Lightning, would find those rails closed through licensed local providers.
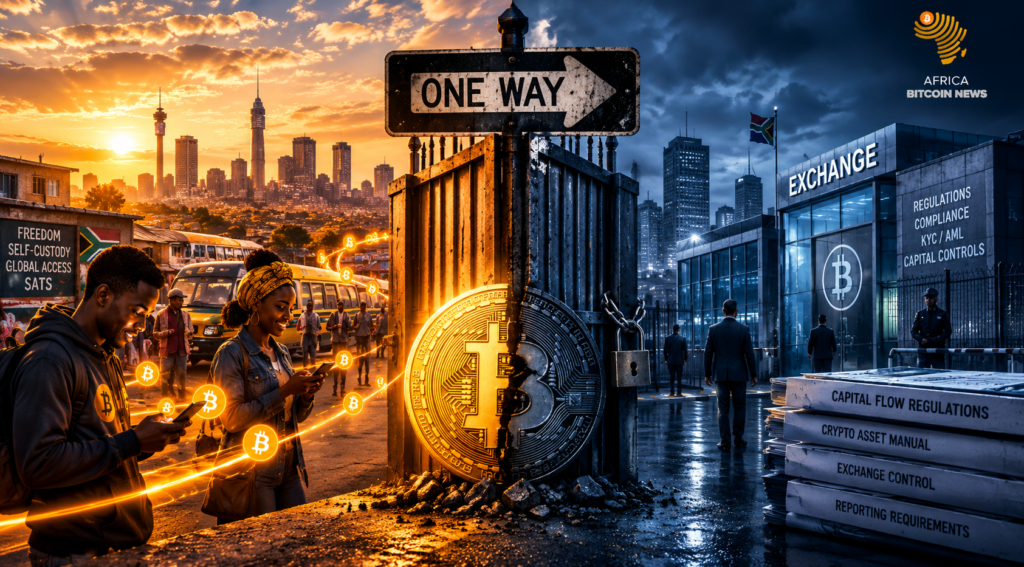
Second, self-custody becomes a one-way street. Residents can still withdraw Bitcoin from a licensed South African platform to a non-custodial wallet. Moving those same coins back onto a regulated domestic platform is classified as non-permissible. The regulated ecosystem turns into a gated compound: easy to leave, hard or impossible to re-enter cleanly.
These rules sit inside the broader Draft Capital Flow Management Regulations that are intended to modernise the 1961 Exchange Control framework. The intent is understandable — monitoring capital flows and reducing regulatory arbitrage. The method is the problem. Equivalent economic activity receives unequal treatment solely because it uses blockchain rails instead of traditional banking infrastructure.